Building an ADU in Arizona is a large single expense, so how you pay for it is part of the decision. Below we compare the cost of prefab versus traditionally built ADUs, then walk through the financing paths open to Arizona homeowners: cash-out refinancing, construction loans, HELOCs, and home equity investments.
Investment and Value of an ADU
An ADU affects your finances in two ways. It can be leased, which produces monthly rent, and it adds a second dwelling to the lot, which an appraiser prices against comparable sales in your own neighborhood. Neither figure is a rule of thumb, and both are specific to your street rather than to the metro. We cover what an ADU does to property value and rental income in our guide for Phoenix investors.
Cost Comparison: Prefab vs. Traditionally Built ADUs
When considering building an ADU in Phoenix, it’s important to compare the costs of prefab units versus traditionally built units:
-
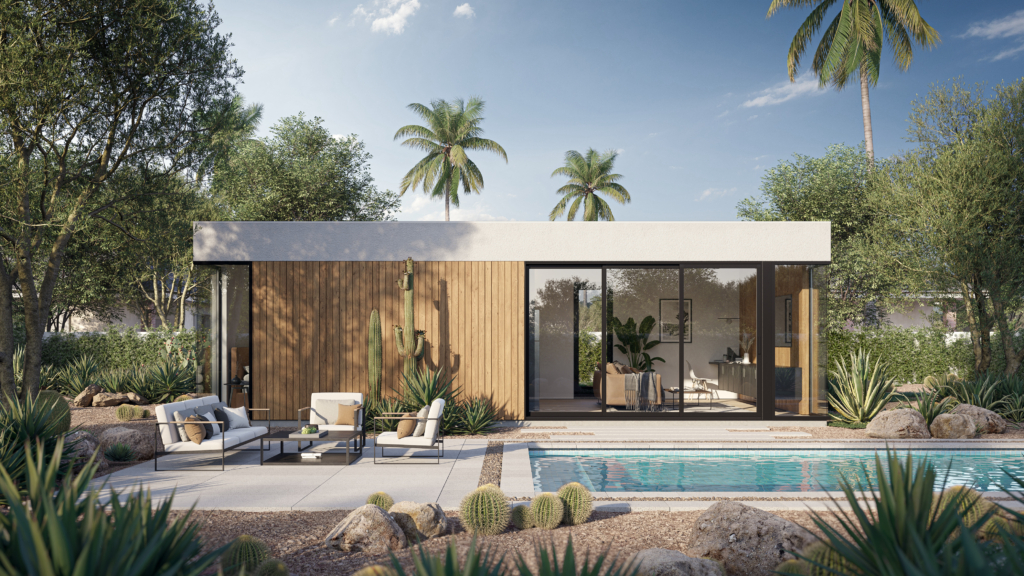
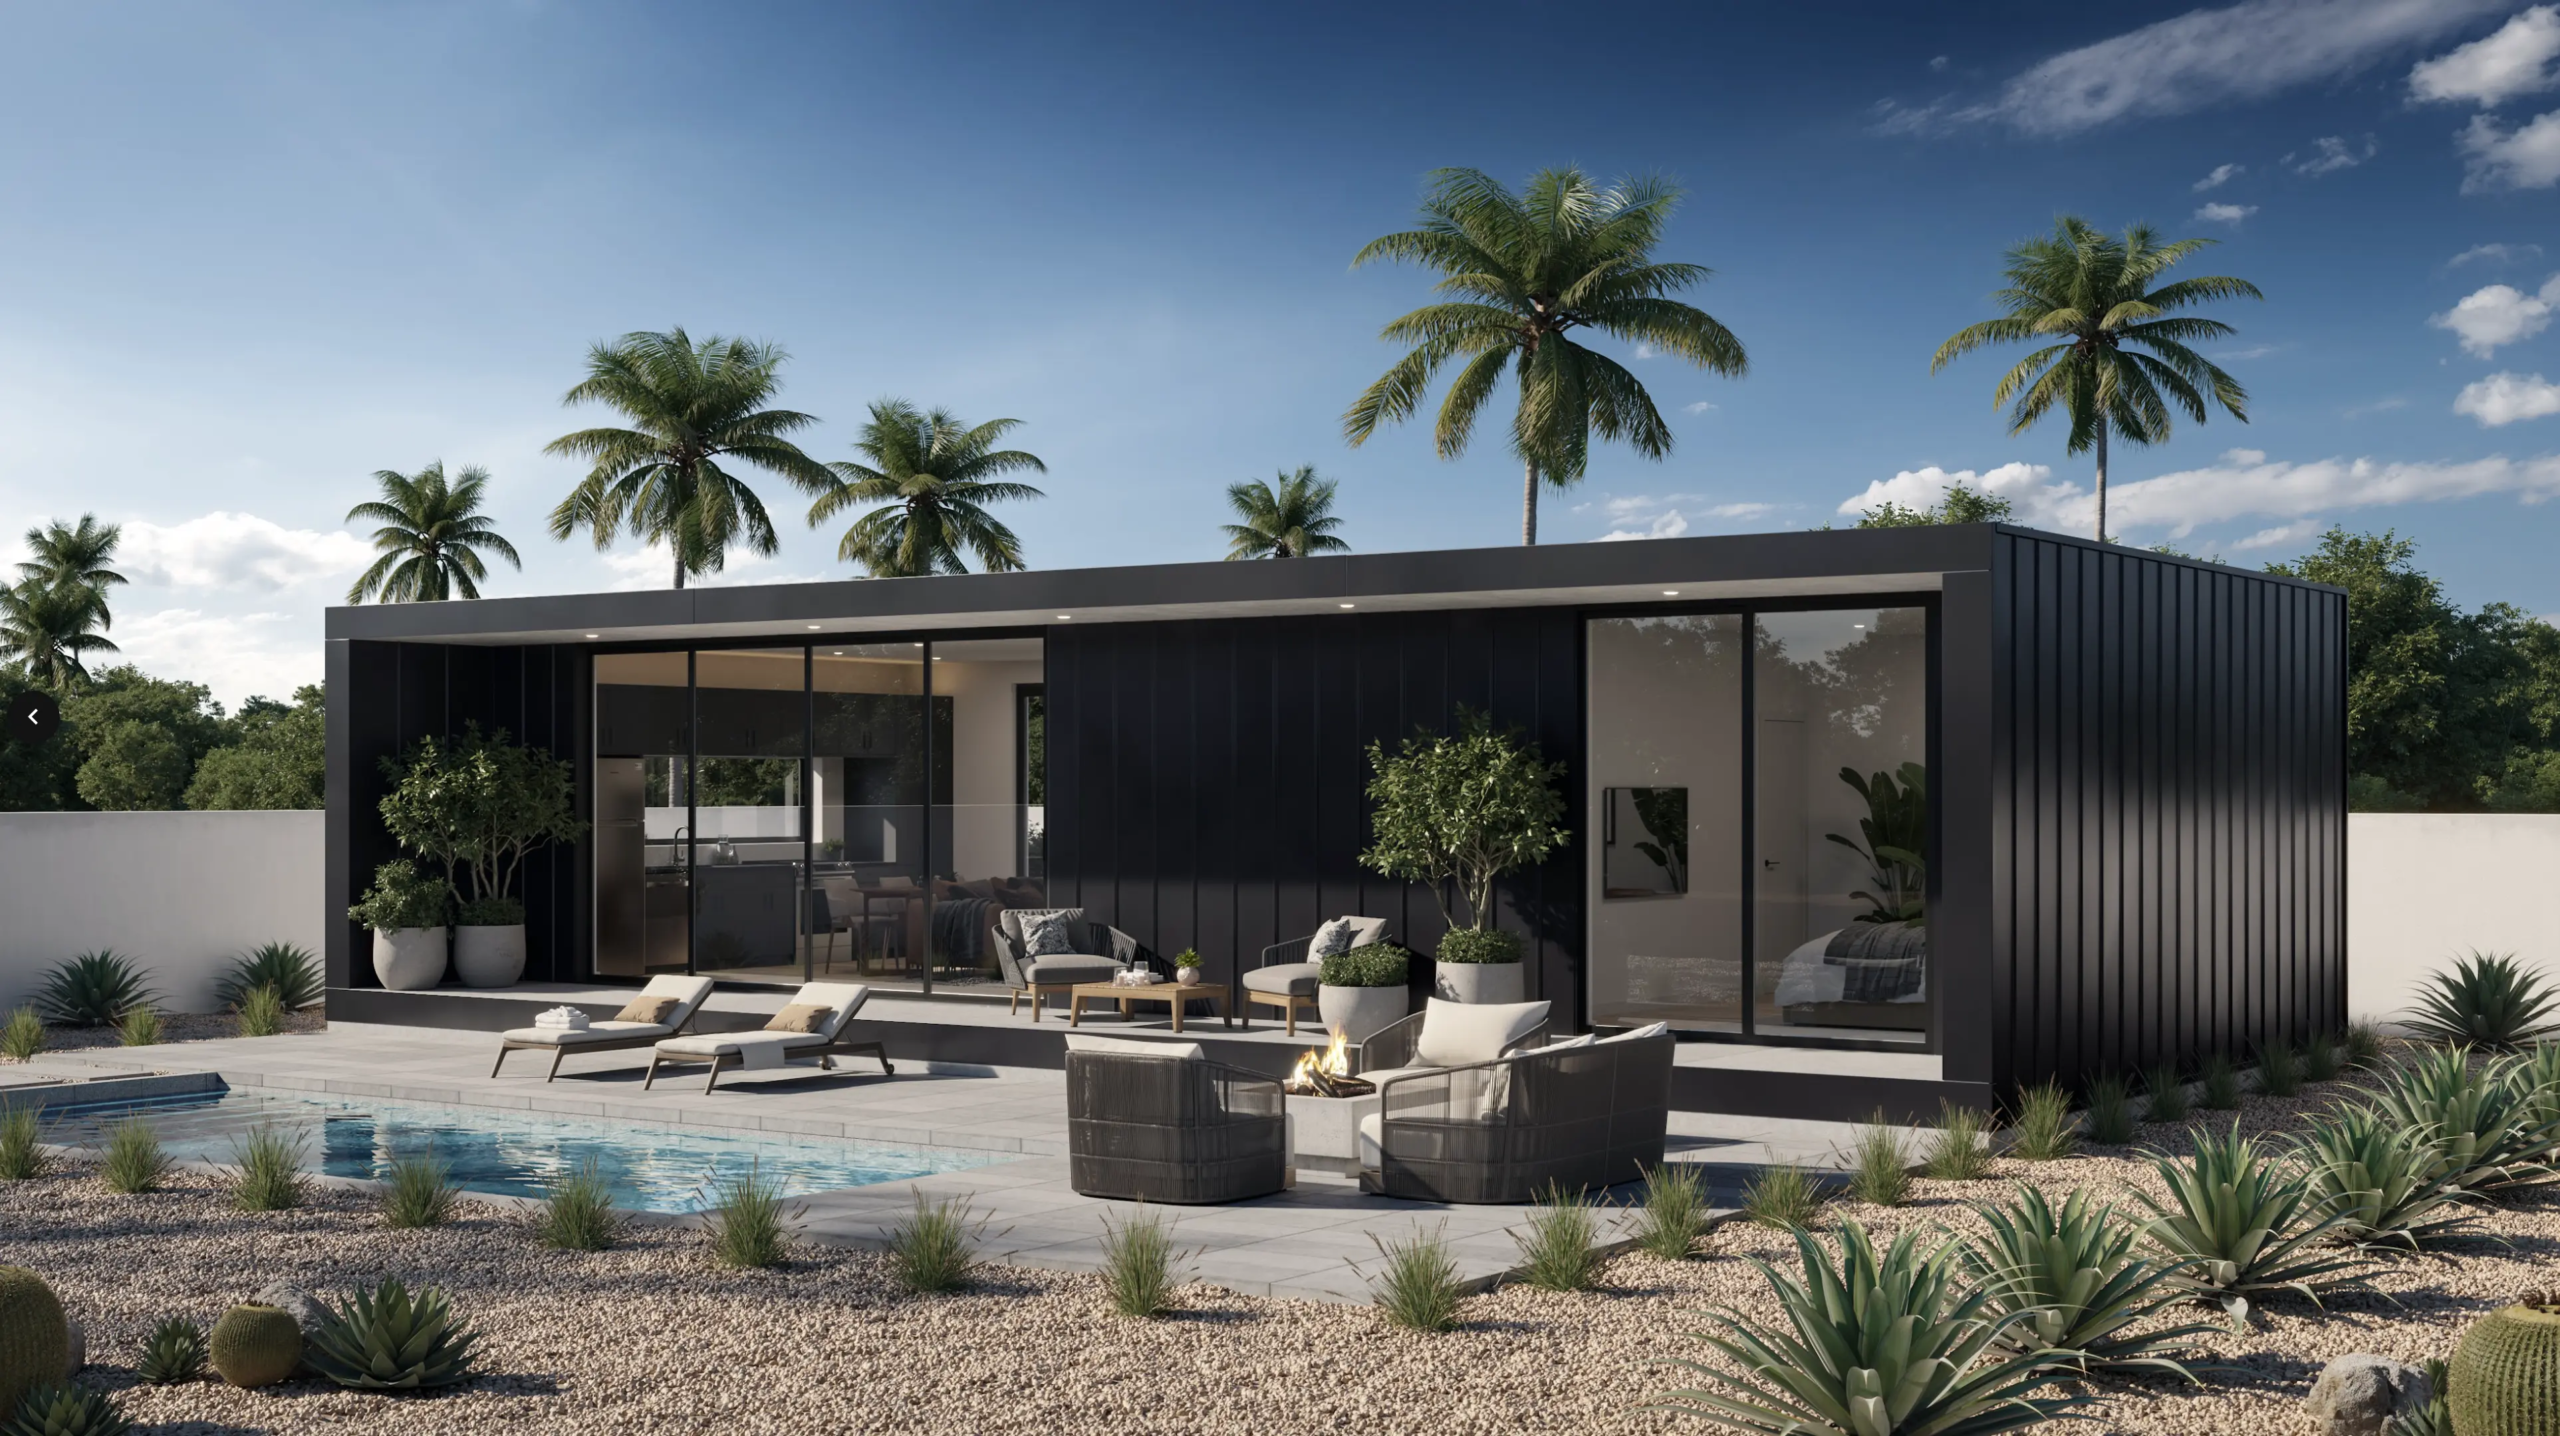
Prefab ADUs: These units are built off-site and then transported to your property. The average starting cost for a more expensive prefab ADU is around $228,000. Prefab units often have the advantage of quicker construction times (although the overall process and timeline can be similar or longer than traditionally built ADUs when considering permitting periods and production lead times). Though there is the novelty benefit of a prefab build, this path is typically more expensive and more time consuming with the additional challenges of permitting.
-
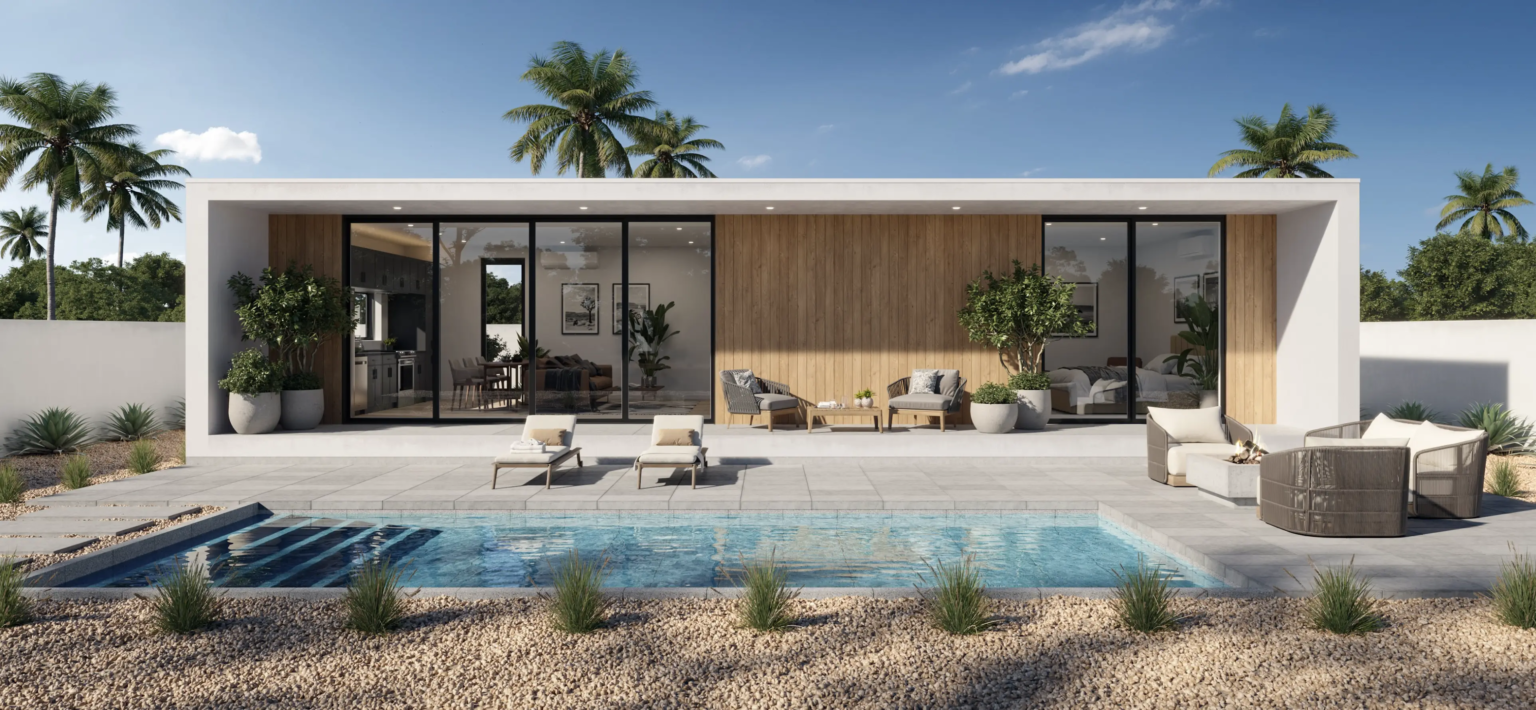
Traditionally Built ADUs: These units are constructed on-site and currently start at $155,000 for MLC’s turnkey Flex model under standard site conditions. Not only do they have a lower initial cost, but the timeline to complete the project can be the same or shorter than a prefab ADU build with much greater financing options. As lenders and banks don’t consider prefab or movable homes to be “Real Property”, they are often much more difficult to finance through conventional methods.
Both options have their pros and cons, and the choice between them depends on factors such as budget, timeline, and personal preference.
Financing Options for Your Phoenix ADU
Financing an ADU in Phoenix can be approached in several ways. Here are some common financing options available to Arizona homeowners:
-
Cash-Out Refinance:
- This option allows you to refinance your existing mortgage and take out a new loan for more than you currently owe. The difference is given to you in cash, which can be used to finance the ADU construction.
- Pros: Potentially lower interest rates, consolidation of debt, and the ability to access a large amount of cash.
- Cons: Extending the term of your mortgage, possible closing costs, and the risk of losing your home if you can’t make the new mortgage payments.
-
Construction Loans:
- These are short-term loans specifically designed to finance the construction of a home or ADU. The loan is converted to a permanent mortgage once the construction is complete.
- Pros: Funds are disbursed as needed during construction, interest-only payments during the build phase, and potential for better interest rates.
- Cons: Stricter qualification requirements, potentially higher interest rates during the construction phase, and the need for detailed construction plans and budget estimates.
-
Home Equity Line of Credit (HELOC):
- A HELOC allows you to borrow against the equity in your home up to a certain limit, typically 80% to 85% of the value of your home. It functions like a credit card, with a revolving line of credit that you can draw from as needed.
- Pros: Flexibility in borrowing, interest-only payments during the draw period, and typically lower interest rates compared to other loans.
- Cons: Variable interest rates, the risk of foreclosure if you can’t repay, and potential fees for accessing the credit line.
-
Home Equity Investments:
- Some companies offer home equity investments, where they provide cash in exchange for a share of your home’s future appreciation. You can receive up to 25% of your home’s equity upfront.
- Pros: No monthly payments, no interest, and the ability to access a significant amount of cash. This kind of financing is available to anyone with equity in their home, regardless of income or credit score.
- Cons: Giving up a portion of your home’s future value, potential impact on your estate, and the need to settle the investment when you sell the home or after a set period.
Conclusion
Financing is one of the first questions to settle on an ADU project. Understanding the costs involved, whether you choose a prefab or traditionally built ADU, and exploring various financing options are crucial steps in the process. By leveraging options like cash-out refinancing, construction loans, HELOCs, and home equity investments, you can find the best solution to finance your ADU project. Compare the options above on rate, term, and what happens if you cannot pay, then choose one before you sign a build contract.
Our Team at Minimal Living Concepts Can Help
Minimal Living Concepts has built over one hundred ADUs within the greater Phoenix area and is a trusted partner for homeowners wanting to add an ADU to their property. We offer:
- Financing Options: We partner with various lenders to provide a range of financing options for your ADU project.
- Thoughtful Floorplans: Our ADU floorplans are designed specifically for the Arizona market and offer highly functional living spaces. See how ADU plans for Arizona lots account for the property, climate, and intended use.
- White-Glove Service: A dedicated project manager will handle everything from start to finish, ensuring a smooth and stress-free experience. Our guide to evaluating a Phoenix ADU builder explains which project-management and local-experience questions to ask.
Ready to Get Started?
Check out our ADUs in person or book a tour at a showroom today. Get the ADU of your dreams with Minimal Living Concepts!